Salesforce has been busy in 2026. Its acquisitions this year span customer service, voice, engagement, research, and analytics, and together they could help turn Agentforce into a much broader customer platform, one that can understand what a customer wants, decide what to do next, and take action across the business. From our perspective at Navirum (a Salesforce consulting company focused on financial services), the logic is pretty clear. Salesforce is betting that its data, distribution, and workflow footprint can bring a lot of scattered AI capabilities into one platform and create a new stream of usage-based revenue. It is a credible strategy, but the hard part will be integration, customer economics, and earning trust in regulated environments.
Information current as of November 3, 2026.
Salesforce Acquisitions in 2026 and Where They Stand
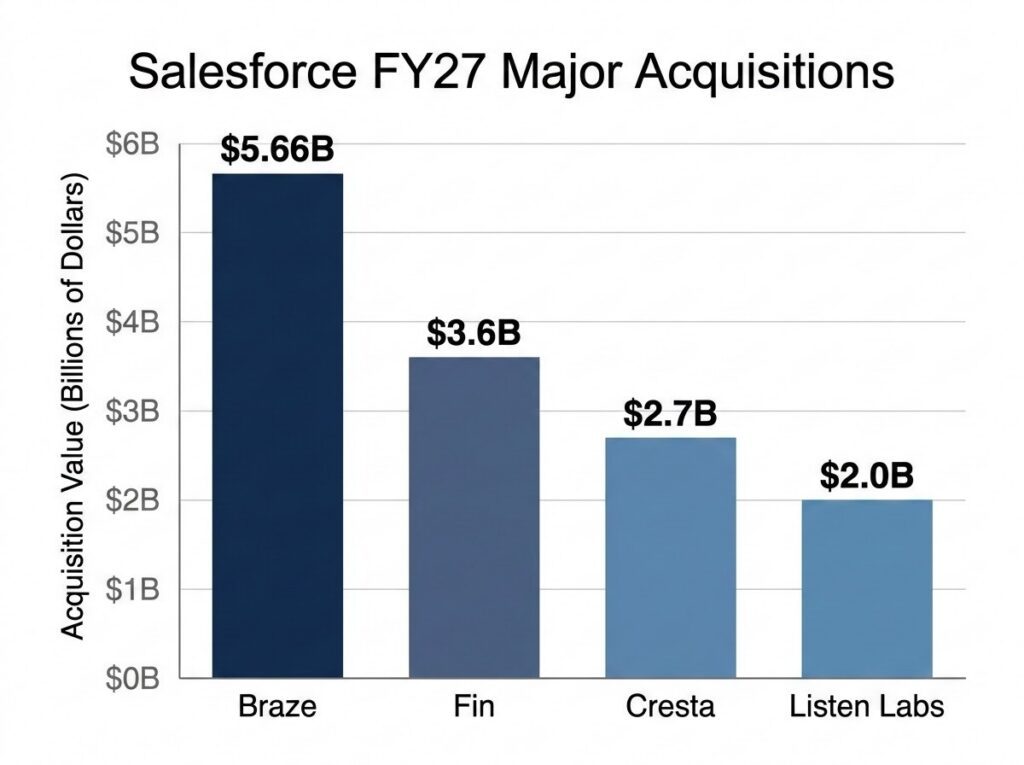
Here are the biggest deals and where they stand. One important detail: Fin has closed, while several of the other transactions are still subject to closing conditions as of this article’s publication date.
- Fin (completed): Salesforce completed its approximately $3.6 billion acquisition of Fin, formerly Intercom, on September 10, 2026. Fin adds a packaged customer-service agent, proprietary models, and an installed base of more than 30,000 companies.
- Cresta (definitive agreement): Salesforce announced an agreement on November 2, 2026 to acquire Cresta, a voice-first customer-experience platform. The reported value is approximately $2.7 billion, and Salesforce expects the transaction to close in the first quarter of its fiscal 2028.
- Braze (definitive agreement): Salesforce agreed to acquire Braze for approximately $5.66 billion in enterprise value. The transaction would add real-time, cross-channel engagement and AI decisioning to Marketing Cloud and the broader Customer 360 architecture.
- Listen Labs (definitive agreement): Listen Labs brings AI-assisted customer research, interview synthesis, and human-simulation capabilities. Salesforce expects the transaction to close in the fourth quarter of fiscal 2027. Neither company disclosed a price; Business Insider reported talks at about $2 billion.
- Loops (definitive agreement): Loops continuously monitors business performance, explains changes in key metrics, and recommends action. Salesforce plans to bring its technology and talent into Tableau after closing.
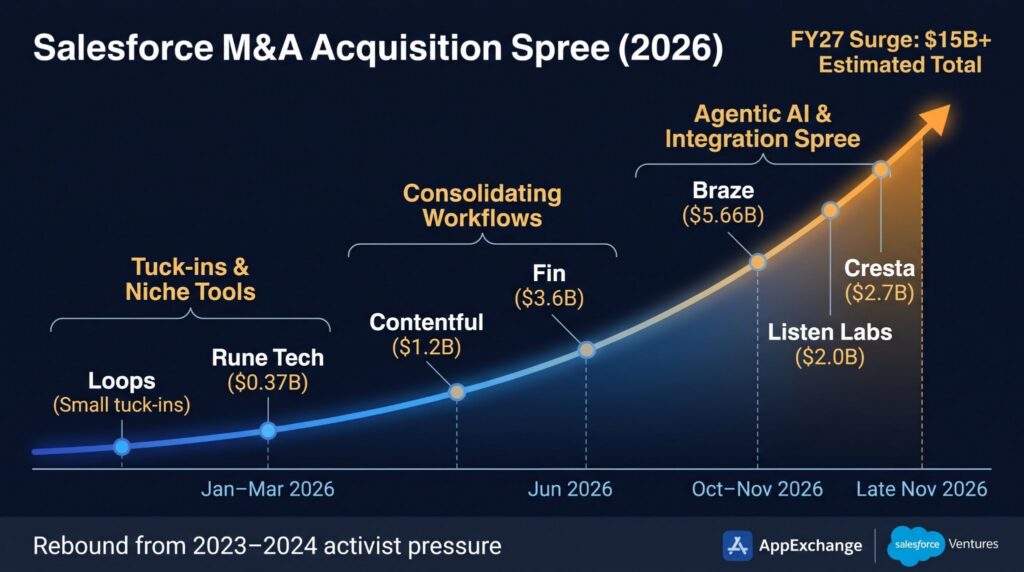
Put the deals side by side and a clear pattern emerges. Salesforce wants to own more of the journey from customer signal to insight, decision, and action. This is bigger than adding a few AI features; it is an attempt to make Agentforce the execution layer across service, marketing, analytics, and data.
What Salesforce Is Building
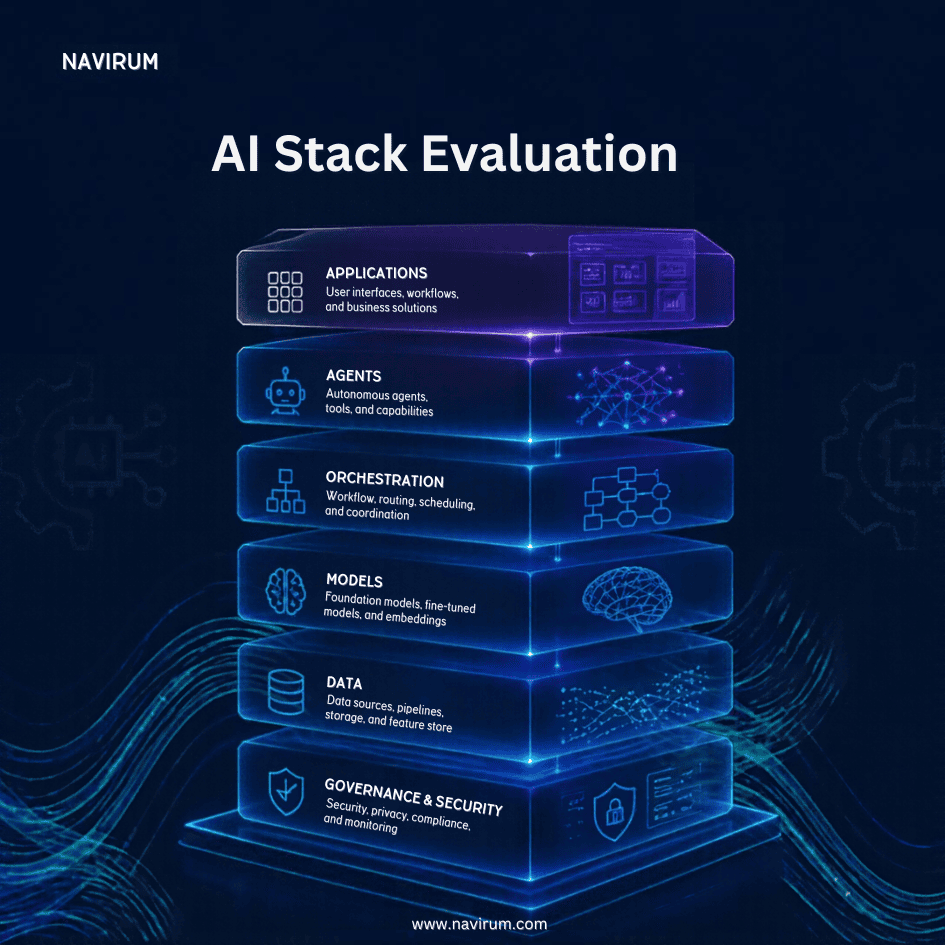
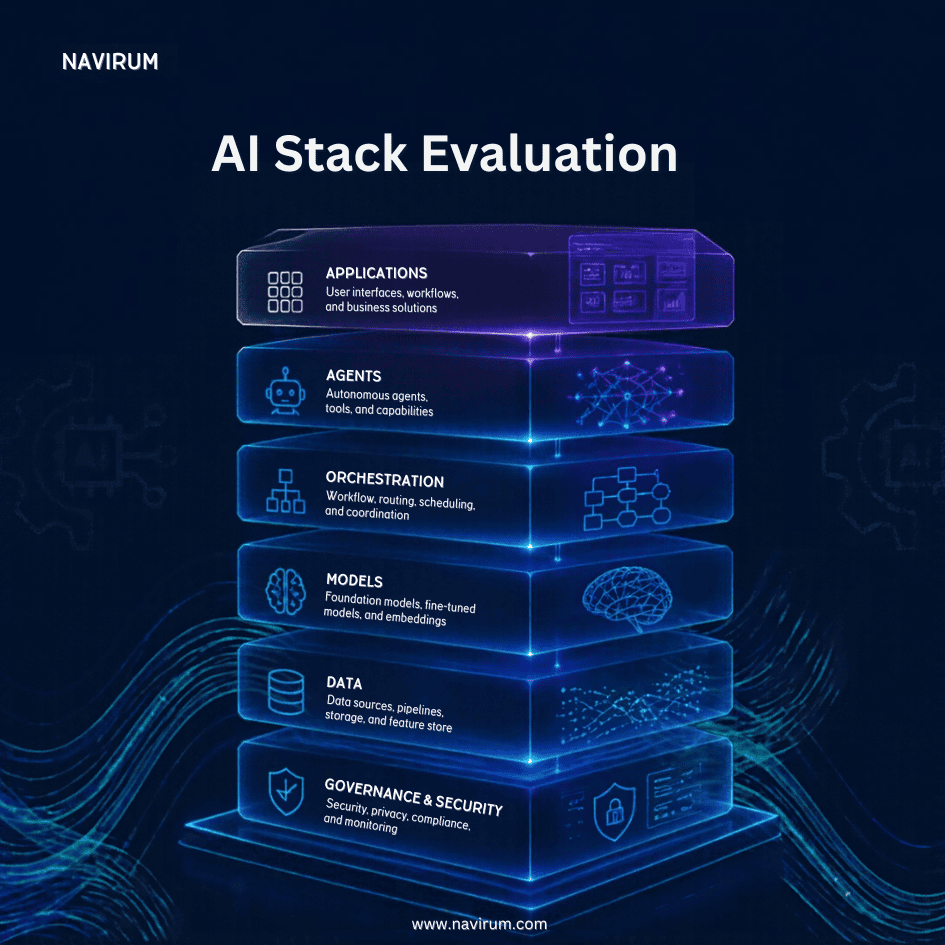
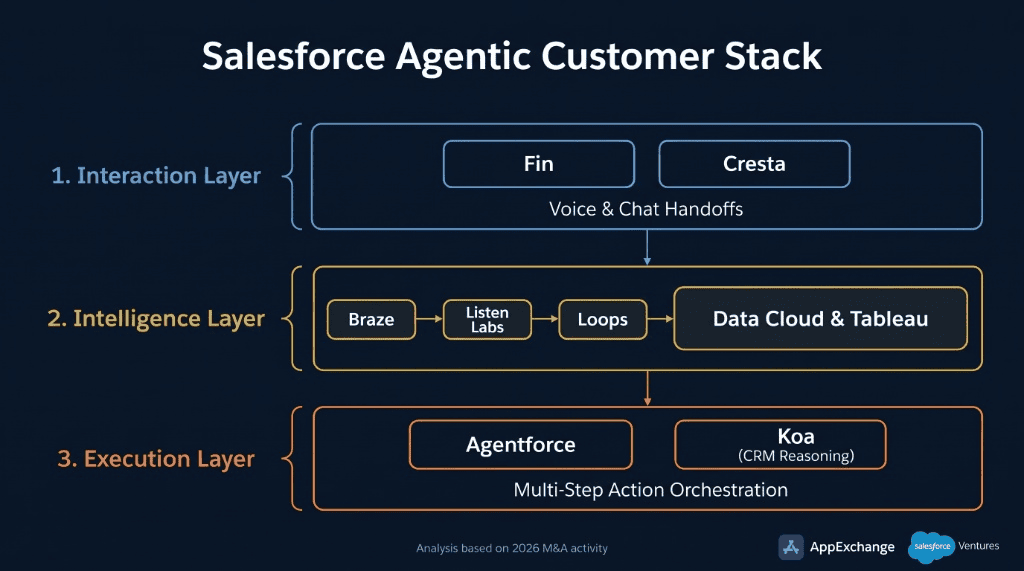
The easiest way to make sense of the strategy is to look at three connected layers. The individual products matter, but the real value will come from whether Salesforce can make them work together as one system.
1. The interaction layer
Fin and Cresta take Salesforce deeper into the actual customer conversation across chat, email, messaging, and voice. That brings Agentforce closer to the moment when someone asks for help, signals an intent, or creates a service risk. It also raises the bar for clean handoffs, reliable records, quality controls, and human escalation.
2. The intelligence layer
Braze, Listen Labs, and Loops bring different kinds of intelligence to the mix: real-time engagement signals, qualitative customer insight, and continuous performance analysis. Paired with Data 360, Tableau, and Informatica, which Salesforce finished acquiring in November 2025 for about $8 billion, they could help Salesforce move beyond storing customer history and get much better at explaining what is happening, as well as what to do next.
3. The execution layer
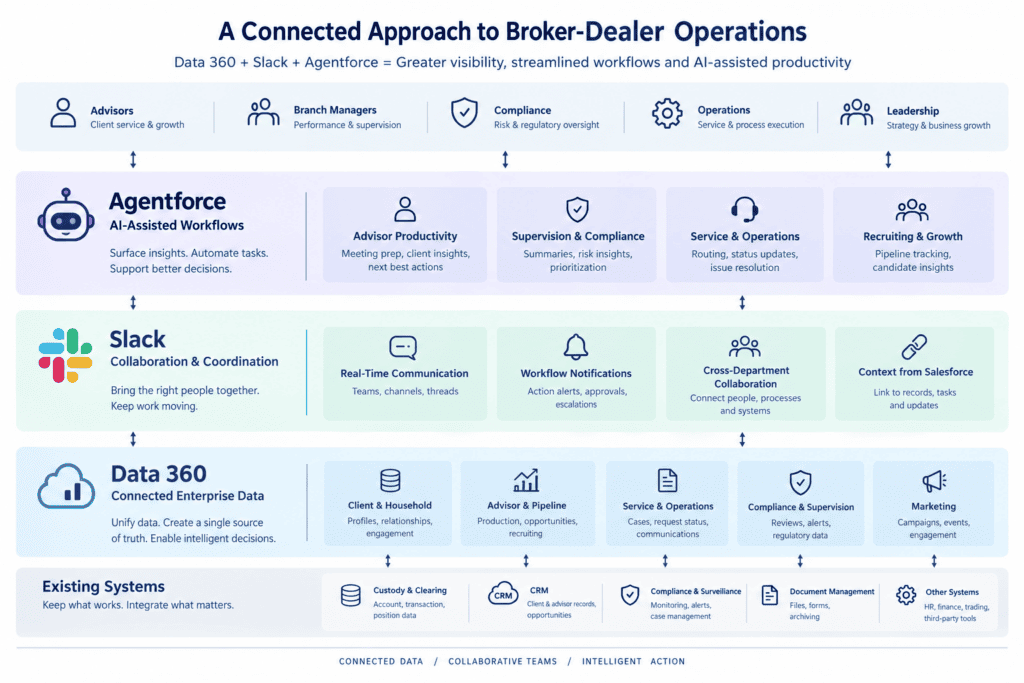
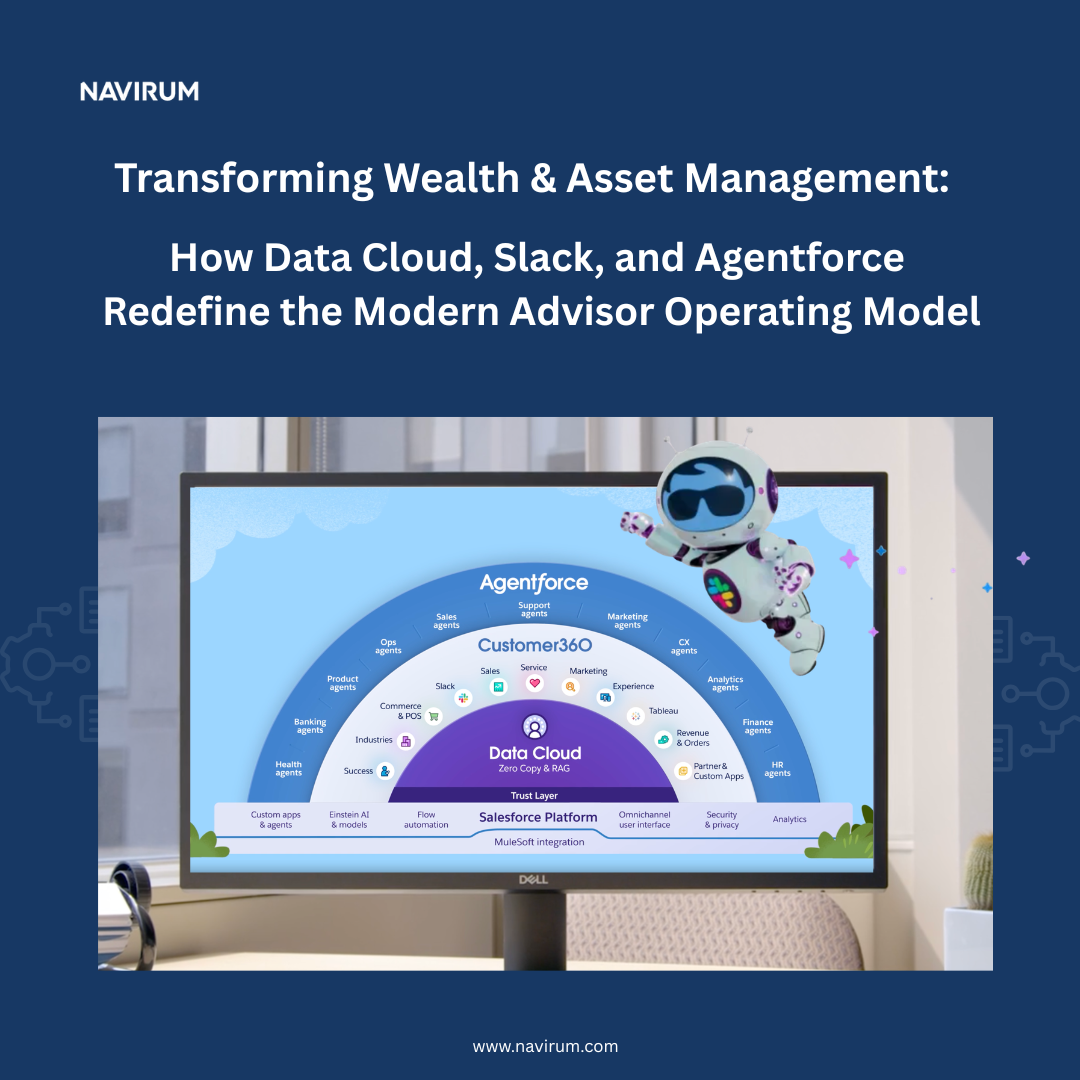
Agentforce is where all of this is supposed to come together. The idea is that specialized agents can share customer context, call approved workflows, and coordinate actions across clouds instead of relying on one general-purpose chatbot. Salesforce is also beginning to build more of the intelligence itself. Koa, developed with NVIDIA and optimized for CRM reasoning, is designed to handle multi-step enterprise workflows inside Salesforce’s trust boundary. If it performs as promised, it could give Salesforce more control over model quality, cost, and data handling. It is an appealing vision, but it will only work if the orchestration, permissions, monitoring, and cost controls are dependable.
What This Means for Salesforce Customers
What Changes for Customers
For customers, the direction is pretty clear: Salesforce wants more of the AI value chain to sit inside its own platform. Customers can already connect models from providers such as Anthropic, Google, and OpenAI, but those calls are still subject to Salesforce usage and billing rules. That gives Salesforce a clear incentive to make its platform more useful and cost-effective rather than simply passing through the expense of general-purpose LLMs. The trade-off is complexity. As the platform expands across data, models, agents, service, marketing, analytics, voice, and governance, small and mid-sized businesses may find the growing feature surface harder to understand, configure, and control.
- More utility from the platform: Salesforce is bringing more data, service, marketing, analytics, and AI capabilities into one stack, which could help customers get more value from the information and workflows they already have.
- More choice, but not necessarily simpler pricing: Customers can use Salesforce-managed, external, or custom models, but they still have to understand Flex Credits, conversations, licenses, Data 360 usage, and implementation costs.
- A broader stack can be harder to run: Large enterprises may value the breadth, but smaller businesses risk paying for—or having to govern—capabilities they do not really need. For many customers, getting the most from Salesforce will depend on a clear roadmap and the right implementation or managed-service partner to help configure, govern, optimize, and support the platform.
What to Do Now
None of these deals will change your Salesforce org overnight, but a few decisions are worth making before the integrations land.
- Time renewals around Salesforce’s fiscal year-end: Salesforce’s fiscal year ends January 31. Before you sign a renewal or expansion, ask how acquired products such as Fin, Braze, and Cresta are likely to be packaged, and keep enough flexibility to adopt them later without renegotiating from scratch.
- Map where you overlap: List the tools you already pay for in chat, service, voice, marketing engagement, customer research, and analytics. If you use Intercom, Braze, or a voice-AI vendor today, note renewal dates and data dependencies so you can decide whether to consolidate on your own timeline.
- Put cost controls in place before you scale: Set Flex Credit budgets, track consumption in Digital Wallet, and name an owner who reviews usage every month. Pilot usage rarely predicts production volumes.
- Settle governance before agents go live: Decide which data agents can use, what permissions they get, how actions are logged, and when a human steps in. Regulated firms should read the financial services section below for the supervisory and recordkeeping side.
- Prove one workflow first: Start with a single measurable process, such as service case triage or post-meeting client follow-up, and show the result before adding more agents or clouds.
Why Salesforce May Have an Edge
Salesforce has more going for it than a big balance sheet. AppExchange, Salesforce Ventures, and a large enterprise customer base give it a useful view into emerging technologies and how customers are actually adopting them. A startup that already works well with Salesforce may also be easier to integrate than a product coming from completely outside the ecosystem.
The Ventures portfolio gives Salesforce another window into where enterprise AI is heading. Investments in companies such as Anthropic and Cohere do not mean an acquisition or native integration is inevitable. They are better read as strategic possibilities—and as clues about what Salesforce thinks will matter, including model choice, retrieval, safety, and enterprise deployment.
John Somorjai oversees both strategic transactions and Salesforce Ventures, which should make it easier to connect investment themes with corporate development. That does not mean there is a neat formula in which every venture bet becomes an acquisition; that part remains our interpretation of the broader possibilities.
Why Investors Care
This is where the story gets interesting for investors. Salesforce already has a huge installed base using its data, workflows, identity model, and commercial agreements. If the integrations work, it can bring the acquired capabilities to those customers faster, encourage more cross-cloud adoption, and make agentic workflows easier to deploy.
Pricing is the other piece of the puzzle. Salesforce now sells Agentforce through conversation-based pricing, Flex Credits, and user-based options. That gives revenue a chance to grow with activity rather than employee count alone, but it also means customers have to watch the cost of every agent action, conversation, prompt, translation, and voice workflow.
So the real question is not simply whether Agentforce adoption grows. It is whether customers keep using it, expand their commitments, and see enough value to justify the spend. Digital Wallet visibility and practical cost controls may matter almost as much as the headline price of an individual action.
How Has Salesforce Stock Held Up?
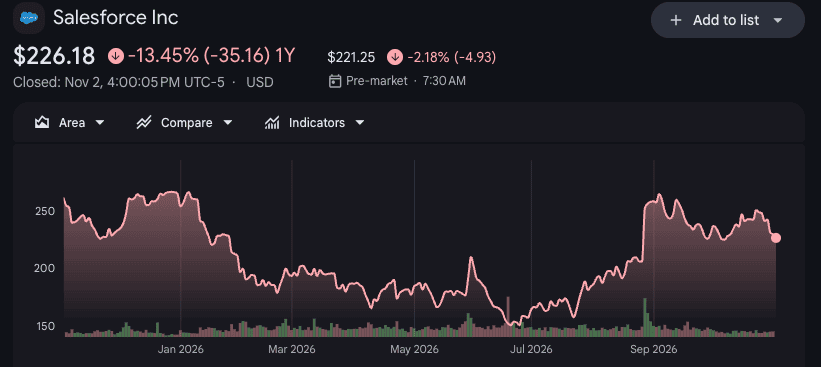
So how has Salesforce stock actually held up during all this dealmaking? Not brilliantly, but the peer comparison makes the picture a bit more interesting. CRM is down roughly 13% over the past 12 months (as of November 2), versus about 51% for HubSpot and 42% for ServiceNow, while Microsoft has been much steadier at around 2% down. Salesforce still closed at $226.18 on November 2, well below its $269.11 52-week high, but about 55% above the $146.32 low it hit in June. So Salesforce has not exactly been a standout, but it has held up much better than some high-growth SaaS peers. The market seems less worried than it was earlier in the year, though it is not fully sold on the acquisition-and-Agentforce story yet; investors still want to see the deals translate into real usage, revenue growth, and healthy margins.
Where This Could Get Messy
Of course, buying companies is easier than integrating them. Salesforce still has to sort through overlapping products, preserve what made the acquired companies useful in the first place, and make the finished experience feel like one platform rather than a collection of parts.
- Product overlap: Fin, Cresta, Agentforce, Service Cloud, and existing partner products may compete for similar customer-service budgets.
- Customer economics: Consumption pricing can align cost with value, but high-volume activity can also create forecasting difficulty and resistance.
- Platform concentration: Consolidation may reduce the number of vendors while increasing dependence on one strategic provider.
- Execution risk: Large acquisitions can distract management, slow product decisions, or dilute specialist cultures.
- Regulatory exposure: More autonomous actions increase the consequences of inaccurate outputs, excessive permissions, weak recordkeeping, and failed escalation.
So we would not treat this as an automatic win. Salesforce has the reach and platform assets to build a differentiated agentic stack, but it still has to show that customers get better outcomes, manageable costs, and simpler operations.
What This Means for Financial Services Firms
This is where Navirum’s day-to-day lens really matters. Financial services is not the only market for this strategy, but it is one of the best tests of whether the technology is truly enterprise-ready.
Banks, insurers, asset managers, and wealth firms have demanding requirements for supervision, privacy, recordkeeping, access control, and third-party risk.
Supervision and Recordkeeping
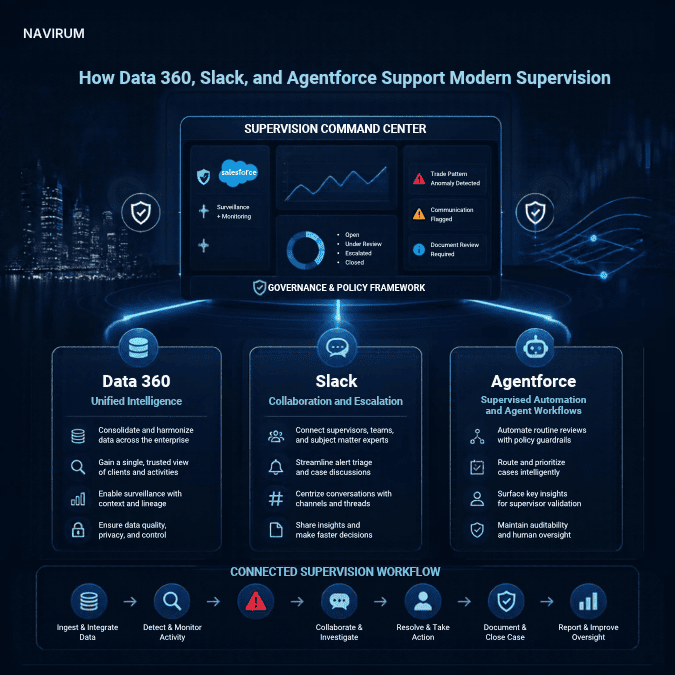
Voice and service agents can produce a huge volume of recommendations and customer communications. In financial services, that activity still has to fit within familiar supervisory expectations. FINRA Rule 3110 and the 2026 Annual Regulatory Oversight Report point to the need for thoughtful testing, monitoring, supervision, and recordkeeping, while the SEC’s fiscal 2027 priorities keep emerging technology and investor protection firmly in view.
Data, Identity, and Model Governance
There probably will not be one model setup that works for every regulated workload. Some firms may use managed external models; others will prefer private retrieval, specific data-residency arrangements, or tightly controlled model access. What they will all need is a strong governance layer around probabilistic systems: approved data, least-privilege permissions, evaluations, human oversight, monitoring, and auditable decisions.
Vendor Rationalization Versus Concentration
Bringing more tools into Salesforce could reduce duplicate integrations and separate third-party assessments. But it does not make third-party risk disappear; it puts more operational dependency in one platform. The amendments to Regulation S-P, including the June 3, 2026 compliance date for smaller entities, make incident response, service-provider oversight, and customer-information safeguards even more important.
That makes financial services a useful scorecard. If Salesforce can deliver agentic workflows that regulated buyers can trust—without making cost or concentration risk unacceptable—the strategy will have credibility well beyond banking and insurance.
What We’ll Be Watching in 2027
- Deal completion and product integration: Watch whether pending transactions close on schedule and whether acquired capabilities receive clear homes across Service Cloud, Marketing Cloud, Tableau, Data 360, and Agentforce.
- Agentforce adoption and usage quality: Growth in customers, annual recurring revenue, actions, and conversations matters, but retention, expansion, and business outcomes matter more.
- Consumption economics: Monitor customer willingness to scale usage, the mix of pricing models, and evidence that Flex Credits create incremental revenue without producing bill shock.
- Cross-cloud adoption: The strongest validation would be customers using acquired capabilities across multiple Salesforce clouds rather than as isolated products.
- Regulated deployments: Production use in financial services, healthcare, and the public sector will be a stronger signal than pilot announcements.
- Product rationalization: Investors should look for evidence that Salesforce is simplifying overlapping offerings rather than accumulating another layer of complexity.
Our Take
Our read is that Salesforce has a real opportunity to turn these acquisitions into a broader customer platform. Fin and Cresta deepen service automation, Braze expands real-time engagement, Listen Labs adds customer understanding, and Loops strengthens agentic analytics. Agentforce is the piece that could connect it all.
That said, integration will take time. Some products may remain distinct, and customers will want proof that autonomous workflows improve results after implementation and governance costs are included. Multi-agent orchestration is a believable direction, but shared context, clear permission boundaries, reliable handoffs, and cost control will decide whether it becomes a useful operating model or just another layer of software complexity.
The strategy makes sense on paper. Now Salesforce has to make it work. The best proof will be better customer outcomes, durable consumption revenue, and trust from the enterprise buyers with the highest standards.
Frequently Asked Questions
Salesforce’s five largest deals of 2026 are Fin, which closed on September 10, 2026, and pending agreements for Braze, Cresta, Listen Labs, and Loops. As of November 3, 2026, those four were still subject to closing conditions.
Braze, at approximately $5.66 billion in enterprise value. Fin, at approximately $3.6 billion, is the only one of the five largest deals that has closed so far.
Yes. Salesforce completed its acquisition of Informatica in November 2025, in a deal valued at about $8 billion. Informatica’s data integration and governance tools strengthen the data foundation behind Data 360 and Agentforce, which the 2026 deals build on.
More capability in one platform, but also more to govern. Banks, insurers, and wealth firms still need supervision, recordkeeping, least-privilege permissions, and third-party risk oversight around any agentic workflow, and consumption pricing makes cost monitoring part of that work.
Sources and Methodology
Primary company and regulatory sources were used for transaction status, pricing, governance, and compliance claims. Secondary reporting is identified where an official announcement did not disclose a deal value.
- Salesforce Mergers and Acquisitions archive: https://www.salesforce.com/news/topics/mergers-and-acquisitions/
- Salesforce agreement to acquire Cresta: https://www.salesforce.com/news/stories/salesforce-signs-definitive-agreement-to-acquire-cresta/
- Salesforce agreement to acquire Braze: https://www.salesforce.com/news/press-releases/2026/10/20/salesforce-signs-definitive-agreement-to-acquire-braze/
- Salesforce agreement to acquire Listen Labs: https://www.salesforce.com/news/stories/salesforce-signs-definitive-agreement-to-acquire-listen-labs/
- Salesforce agreement to acquire Loops: https://www.salesforce.com/news/stories/salesforce-signs-definitive-agreement-to-acquire-loops/
- Salesforce completion of Fin acquisition: https://www.salesforce.com/news/press-releases/2026/09/10/salesforce-completes-acquisition-of-fin/
- Salesforce Agentforce pricing: https://www.salesforce.com/agentforce/pricing/
- John Somorjai, Salesforce corporate development and investments: https://www.salesforce.com/news/john-somorjai-2/
- SEC fiscal 2027 examination priorities: https://www.sec.gov/newsroom/press-releases/2026-109-sec-announces-fiscal-year-2027-examination-priorities
- SEC Regulation S-P small-entity compliance guide: https://www.sec.gov/file/regulation-s-p-small-entity-compliance-guide
- FINRA 2026 Annual Regulatory Oversight Report: https://www.finra.org/sites/default/files/2025-12/2026-annual-regulatory-oversight-report.pdf
- Dealroom reporting on the Cresta transaction value: https://dealroom.co/news/168989-salesforce-to-buy-voice-ai-startup-cresta-for-2-7b/
- Navirum, AI governance for U.S. financial services: https://navirum.com/2026/11/02/ai-governance-framework-financial-services/
- Salesforce investor-relations stock information: https://investor.salesforce.com/stock-info/
- Salesforce announcement of the Koa CRM reasoning model: https://www.salesforce.com/news/press-releases/2026/09/15/koa-reasoning-model/
- Salesforce Agentforce Models API developer guide: https://developer.salesforce.com/docs/ai/agentforce/guide/models-api.html
- Salesforce Help, generative AI usage and billing: https://help.salesforce.com/s/articleView?id=ai.generative_ai_usage.htm
- SiliconANGLE reporting on the Listen Labs transaction value: https://siliconangle.com/2026/10/01/salesforce-to-acquire-ai-customer-research-startup-listen-labs-in-reported-2b-deal/
- Peer 12-month stock returns, HubSpot: https://tickerlandia.com/en/stocks/hubspot-hubs/returns
- Peer 12-month stock returns, ServiceNow: https://tickerlandia.com/en/stocks/servicenow-now
- Peer 12-month stock returns, Microsoft: https://tickerlandia.com/en/stocks/microsoft-msft
- Salesforce completion of the Informatica acquisition: https://www.salesforce.com/news/press-releases/2025/11/18/salesforce-completes-acquisition-of-informatica/